Roof insurance claims, done properly
We document the damage the way the adjuster documents it, meet them on the roof, reconcile the scope line by line, and build the roof the claim paid for — with your deductible collected exactly as Texas law requires.
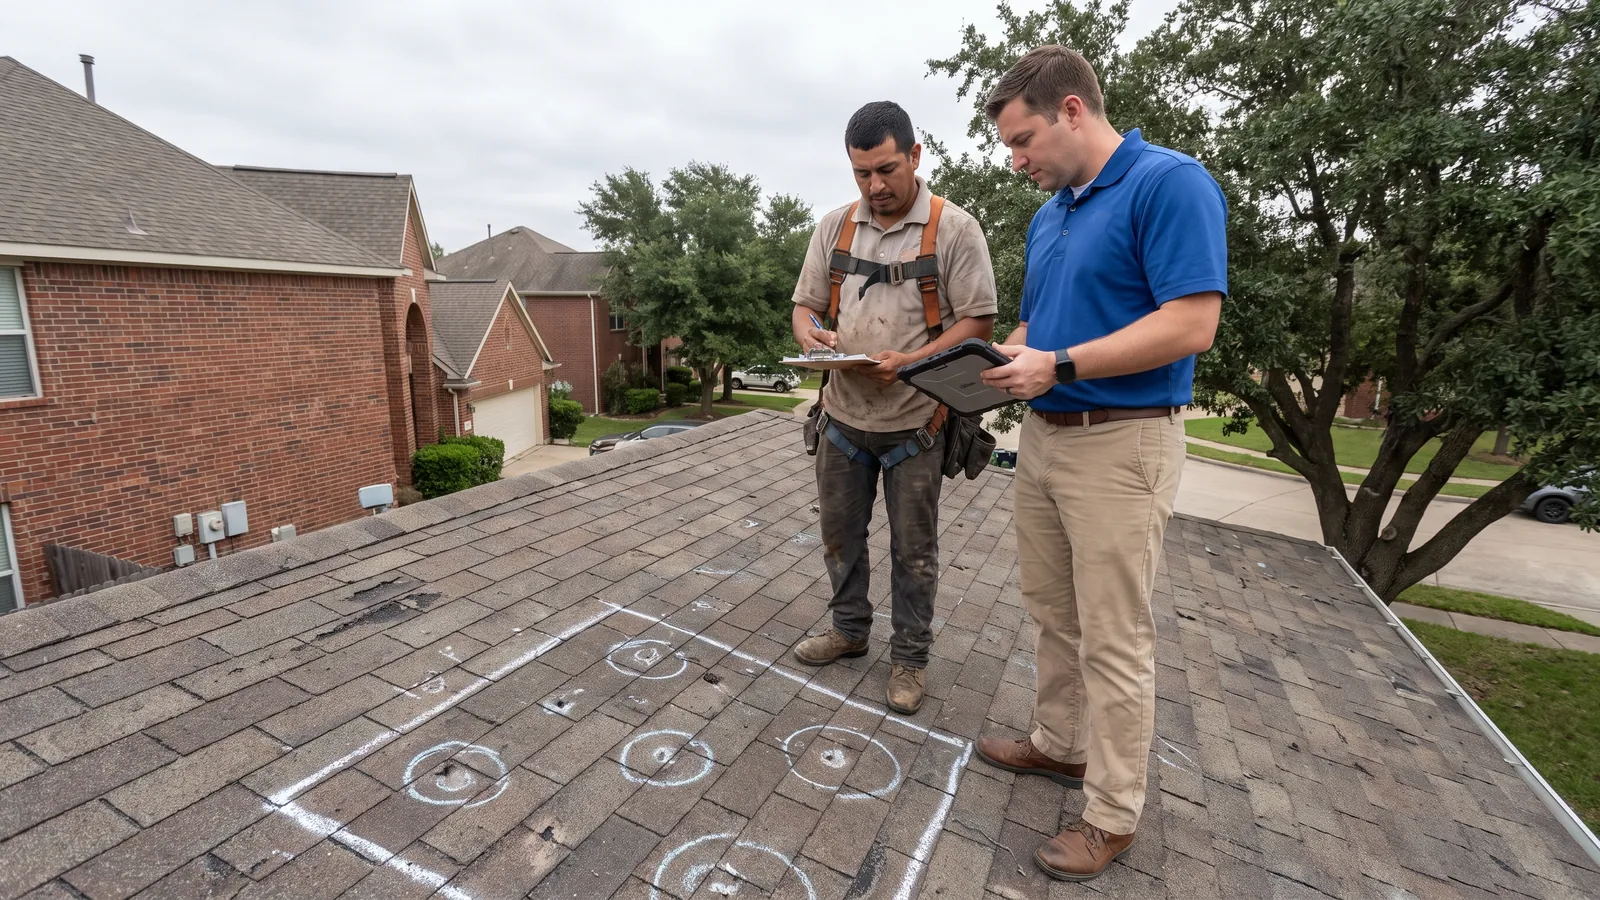
A roof claim in Texas is a paperwork process with a roof attached, and most of the frustration people have with claims comes from the paperwork side: a scope that's missing the drip edge and the ridge vent, a depreciation holdback nobody explained, a supplement that never got filed, a contractor who cashed the first check and vanished. We've built our claims process to handle every one of those steps, in order, so the roof you get is the roof your policy paid for.
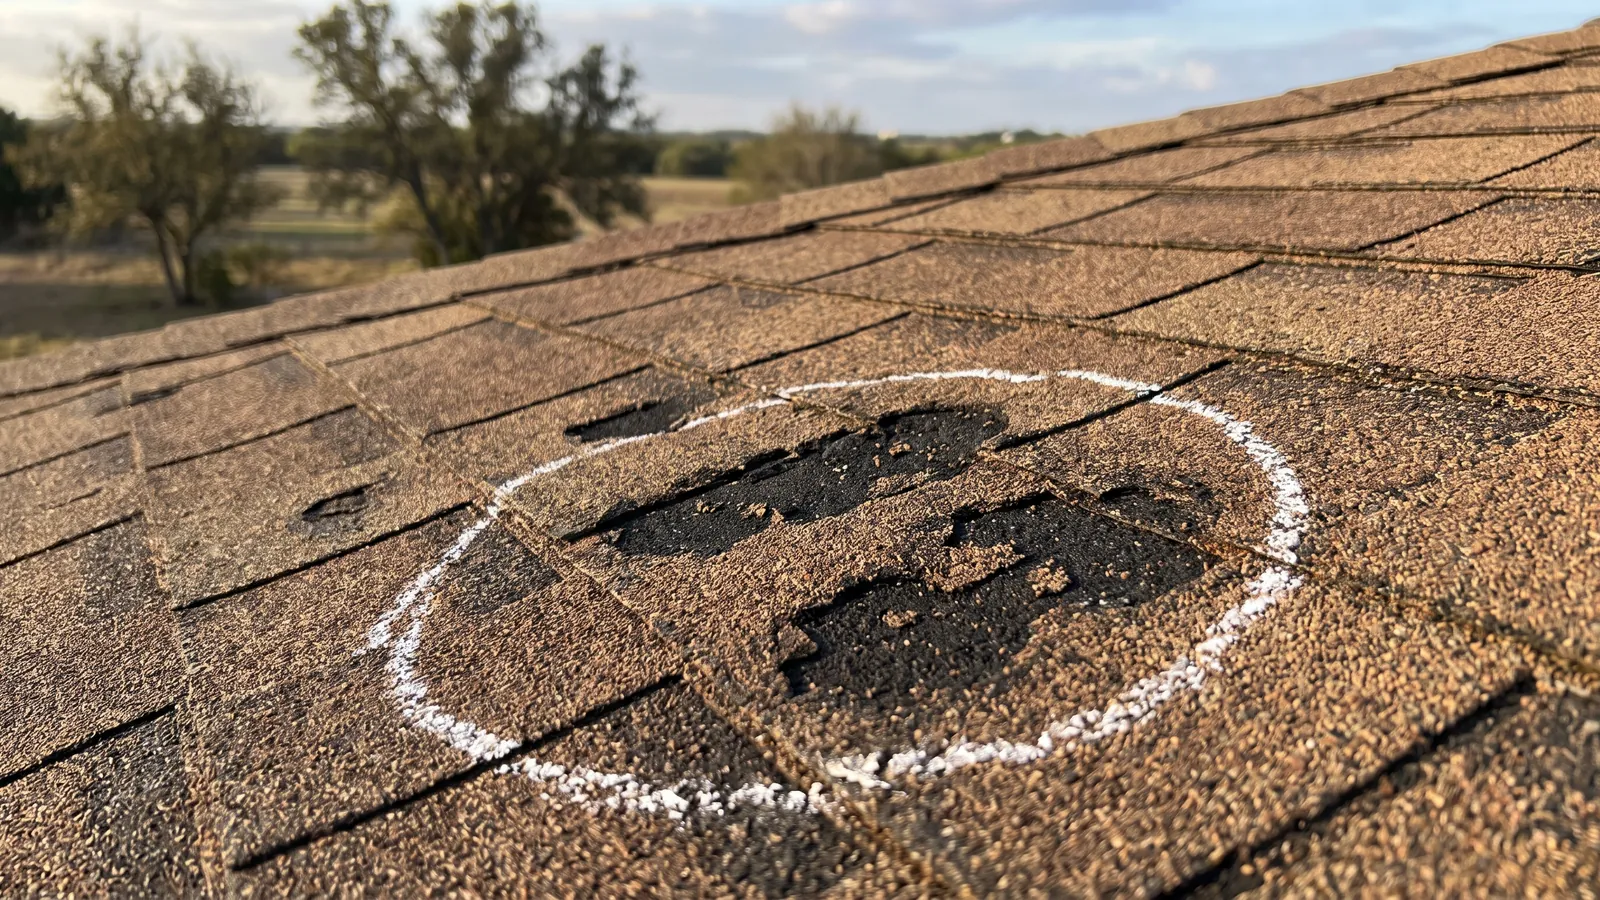
The process: free inspection with a test square on every slope and a photo of every hit; an honest verdict on whether the damage clears your deductible (often it doesn't, and we'll say so); you file the claim; we meet the adjuster on the roof with our photos and a measured diagram; we reconcile their scope against ours and file a supplement for anything missed — decking, code-required items, the second layer; you receive the actual cash value check; we build the roof; we send the completion certificate and the insurer releases the recoverable depreciation. Your deductible is collected and shown on the invoice, because since 2019 it has been a state-jail felony in Texas to do it any other way.
What's included
Free claim inspection
Test squares, chalk, photos of every hit and every soft-metal dent; a written verdict on whether it's worth filing.
Adjuster meeting
We're on the roof when the adjuster is, with our diagram and photos, so nothing gets missed.
Scope reconciliation
Their Xactimate scope checked line by line against ours; supplements filed for decking, code items, missed slopes.
Depreciation recovery
Completion certificate and final invoice sent so the recoverable depreciation is released to you.
Deductible done right
Collected and itemized on the invoice, as Texas Insurance Code chapter 707 requires. Never waived, never rebated.
Code upgrades
Ordinance-or-law coverage used for drip edge, ice-and-water and ventilation the code now requires.
What a roof claim costs you in New Braunfels, TX
| Job | Typical price | Notes |
|---|---|---|
| Claim inspection & documentation | Free | After any named storm |
| Adjuster meeting | Included | We come to the appointment |
| Supplement preparation | Included | Filed with photos and measurements |
| Roof replacement under a claim | Your deductible | Plus any upgrades you choose |
| Class 4 upgrade over the scope | $1,200 – $2,500 | Often refunded through the premium discount |
| Re-inspection when a claim is denied | Free | Second opinion with a written report |
On a covered claim your out-of-pocket is your deductible plus any upgrades you choose. We'll show you the math before you file.
Recent work
Questions we get about insurance claims
Should I file a claim?
Only if the damage is clearly more than your deductible — on a $400,000 house with a 2% deductible that's $8,000 of damage. A repair below that is money out of your pocket either way, plus a claim on your record. We tell you which side of the line you're on before you call the insurer.
Can you waive or pay my deductible?
No. Texas made it a crime in 2019 (HB 2102, now Insurance Code chapter 707) for a contractor to waive, absorb or rebate a deductible, and insurers can demand proof you paid it before releasing depreciation. Anyone offering to eat your deductible is offering to commit fraud with you.
What is recoverable depreciation?
Your insurer pays the claim in two parts: the depreciated value of the old roof up front, and the rest — the 'recoverable depreciation' — after the roof is actually built and you submit the final invoice. We handle that submission. Some policies (ACV-only) don't pay the second part; check yours.
What if the adjuster says there's no damage?
Ask for a re-inspection with your contractor present — that's your right under your policy. We bring the photos, the test squares and the measurements. If the second adjuster agrees there's no claim, we'll tell you honestly whether we think an appraisal or a complaint to TDI is worth your time.
Do I have to use the roofer my insurance company recommends?
No. You choose the contractor; the insurer only sets the amount. Preferred-vendor programs exist for the insurer's convenience, not yours.