Hail just hit New Braunfels. Now what?
A calm, step-by-step guide for the day after — what to check, who to call, what to sign and what not to sign.
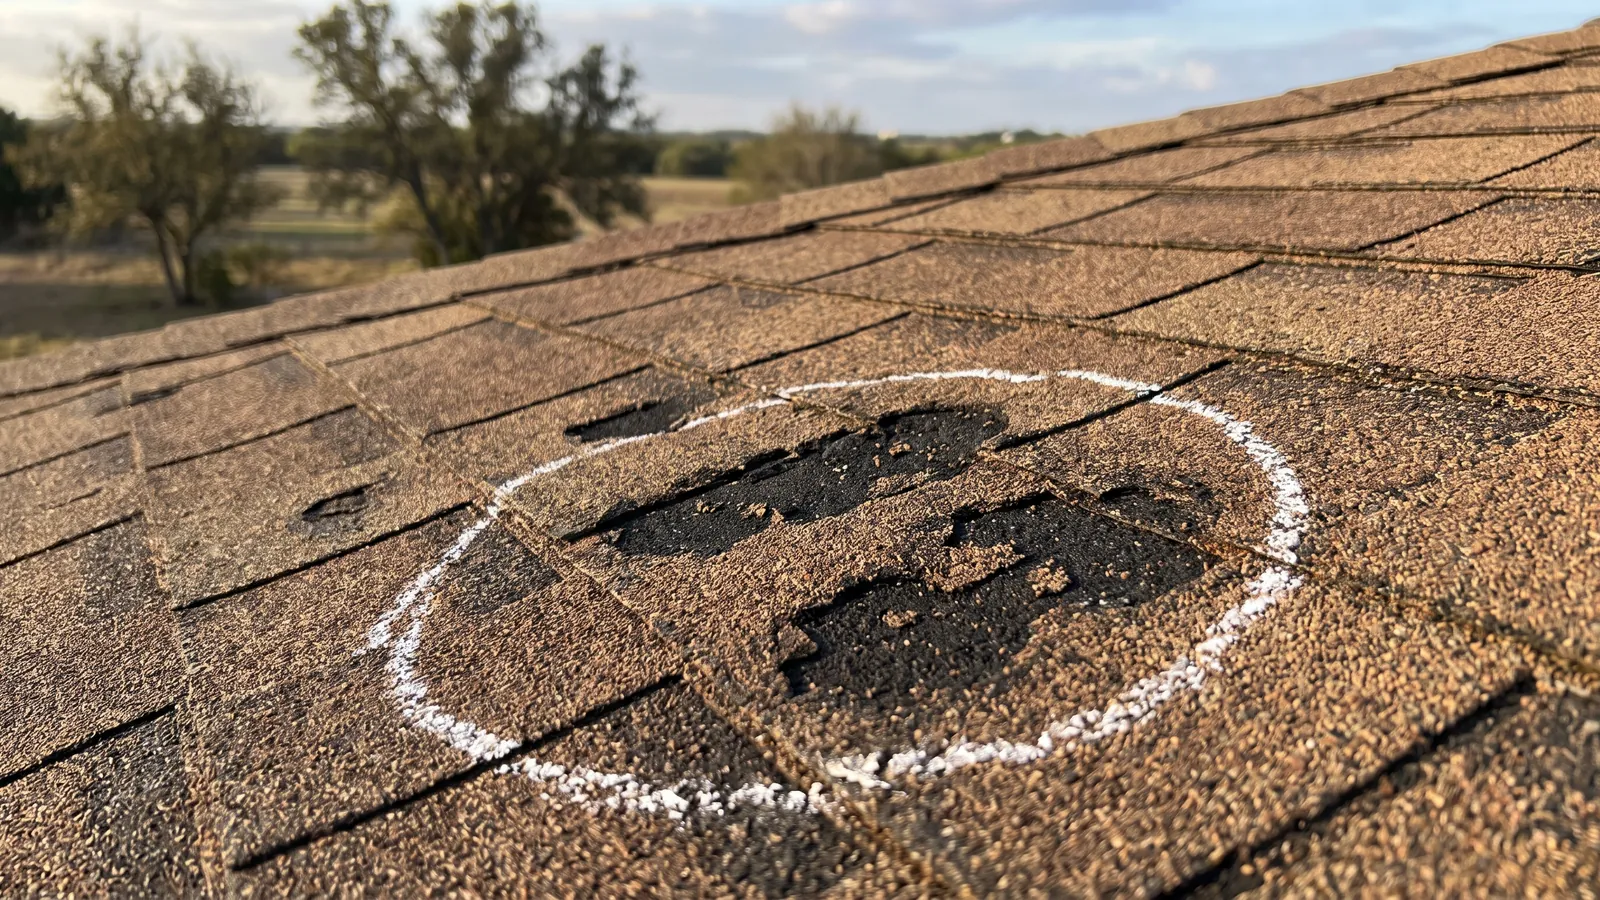
Comal County gets damaging hail almost every spring — March 2022, April 2024 and May 2025 were the recent big ones, and the north side of New Braunfels (78132, Gruene, the Hunter Road corridor) is the most-hit ZIP in the county. Within 24 hours of a storm your neighborhood will fill with out-of-town trucks and door-knockers. This guide is what to do instead of signing the first clipboard.
Step 1 — Look, but stay off the roof
From the ground, check the soft metals: dents in the gutters, downspouts, AC condenser fins, mailbox, the metal on the porch. Look at the window screens and the deck. Check the driveway for shingle granules washed into piles. Any of those is a sign the roof was hit hard enough to matter. Don't climb up — wet shingles after hail are slick, and you won't be able to tell a bruise from a blemish anyway.
Step 2 — Photograph everything, with a date
Hailstones next to a ruler or a coin. Dented gutters. The pile of granules. The screens. Your phone timestamps the photos; they establish the date of loss, which matters if a second storm comes through before your claim is settled.
Step 3 — Get one honest inspection before you call the insurer
A real inspection means a roofer on the roof marking a 10-by-10-foot test square on each slope and counting hits, the way the adjuster will. If there are fewer than 8 to 10 hits per square, most insurers won't total the slope. A good roofer tells you that before you file, because a claim you don't need is a claim on your record. We do this for free after every named storm, and we say 'no claim' when that's the answer.
Step 4 — Don't sign anything on the porch
The storm-chaser playbook: knock, offer a 'free inspection', find damage every time, and get you to sign an assignment of benefits or a contingency agreement that commits you to that company for the whole claim. Some of those forms are legal and some aren't; none of them are in your interest. Take the card, say you're getting a second opinion, and check whether the company has a local address and an 830 number. Texas doesn't license roofers, so a business card proves nothing.
Step 5 — File the claim, and have your roofer meet the adjuster
Call your agent or the claims line, give the date of loss, and ask for the adjuster appointment. Your contractor should be on the roof with the adjuster, with photos and a diagram, so the scope covers everything: every slope that qualifies, the gutters, the vents, the screens, the code items. If the adjuster denies it and you disagree, you can request a re-inspection.
Step 6 — Understand the money
You pay your deductible — 1 or 2 percent of the home's insured value, typically. The insurer pays the depreciated value of the roof now and the rest after the roof is built. Nobody can legally waive your deductible in Texas; that's a felony for the contractor and a problem for you. Details in our deductible law guide.
Step 7 — Build the roof that survives the next one
Class 4 impact-resistant shingles cost a little more than the scope pays and usually earn a premium discount that repays the difference. Metal, on a Hill Country house, is the permanent answer. Either way: full tear-off, ice-and-water in the valleys, ridge vent, six nails, city permit.
Common questions
How do I know if hail damaged my roof?
You mostly can't from the ground. Dented gutters, damaged screens and granule piles are the tell-tales; the roof itself needs someone up there marking a test square. A free post-storm inspection from a local company is the right first step.
How long do I have to file a hail claim in Texas?
Most Texas policies require the claim within one year of the date of loss, and some now say as little as six months. That's why the date-stamped photos matter and why the free inspection should happen within weeks, not years.
Will a hail claim raise my rates?
In Texas, a single weather claim usually doesn't raise your individual premium — insurers rate by ZIP and storm history, which is already priced in. Multiple claims in a short period can. We tell you when the damage isn't worth a claim.
Are storm chasers always scammers?
No, but the model is the problem: crews that follow storms have no reason to be here next year when the roof leaks. Ask for a local address, a local number, insurance certificates and references from this county — and never sign an assignment of benefits at the door.
Should I get more than one quote on a claim roof?
Get one honest inspection and at least one written quote. On a claim, the insurer sets the price; what you're choosing is who builds it and what they build it with.
Related: Hail & storm damage service · Insurance claims · Texas deductible law · Emergency tarping